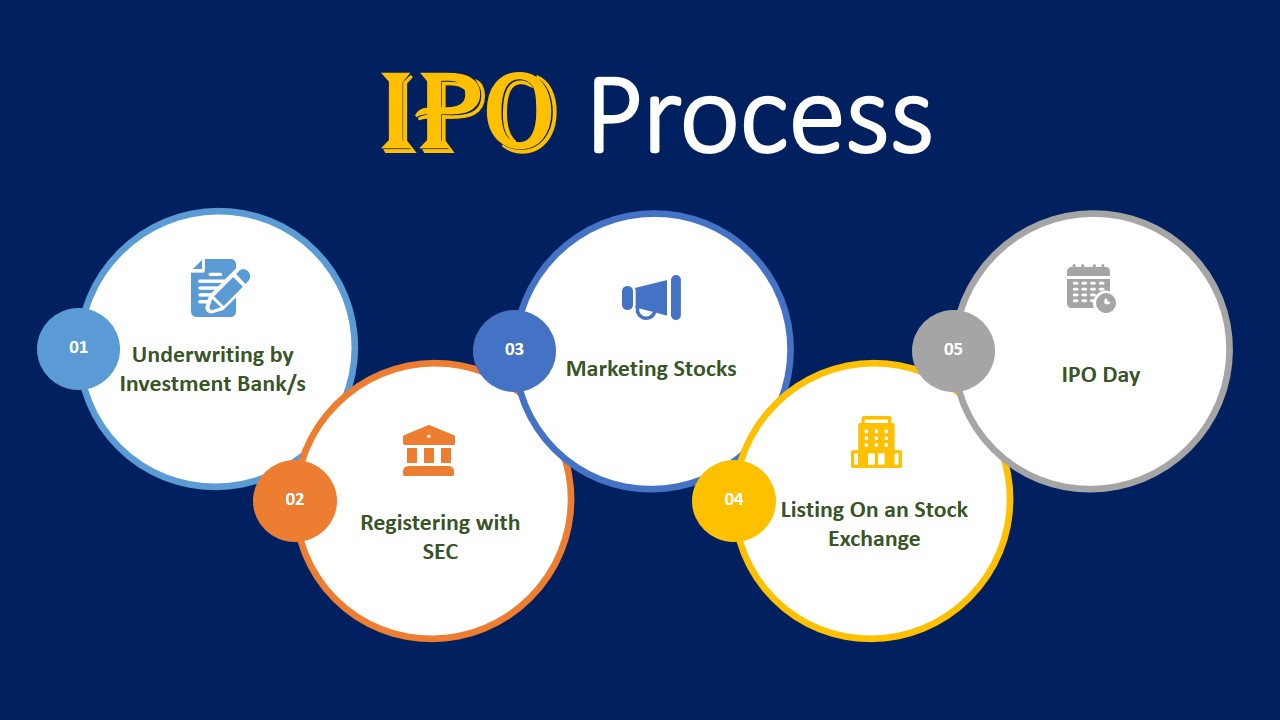
Wall Street spent the entire year waiting for a massive tech and hardware rebound, only to watch the third quarter of 2026 turn into a graveyard of delayed ambitions. Smart-ring maker Oura hit the brakes on its heavily anticipated $2.1 billion Nasdaq debut, joining a growing wave of high-profile companies pulling back from public markets at the eleventh hour.
If you think this is just an isolated case of cold feet, look closer. Across the board, late-stage startups and mature private firms are realizing that public market sentiment is far more fragile than their investment bankers promised. From Bamboo Insurance walking back its plans to Holtec Nuclear withdrawing entirely, the window for a smooth public entry is slamming shut. If you liked this post, you might want to read: this related article.
Why are so many firms scrambling to delay their public offerings right now? It comes down to a clash between boardroom expectations and institutional reality. When valuation targets hit friction, companies with actual cash flow choose to wait out the storm rather than getting butchered on day one.
The Oura Wake-Up Call
When Oura filed to sell 50 million shares at a range of $40 to $44, bankers expected an easy win. The company pointed to massive growth projections, 5.7 million paid members, and strong consumer response to the Oura Ring 5. Yet, right before pricing, leadership pulled the plug. For another angle on this story, check out the latest update from Reuters Business.
Why? Because institutional investors are getting picky. Despite healthy top-line metrics, public buyers are aggressively questioning high valuations in hardware and consumer tech. When you factor in broader macro fears—such as shifting market sentiment indices and rising bond yields—even profitable companies find themselves staring down a hostile trading desk.
Jay Ritter, a finance professor at the University of Florida often called the dean of IPO research, notes that pulling an offering after launching a roadshow is rare. It tells you that the gap between what founders think their company is worth and what Wall Street is actually willing to pay has become too wide to bridge.
Why Q3 2026 Broke the Playbook
The third quarter used to be a standard staging ground for autumn listings. This year, it became a stress test that many private balance sheets simply failed.
Valuation disconnects are the primary culprit. Private rounds in 2024 and 2025 created inflated pricing expectations that public markets refuse to honor today. When institutional buyers look at a tech firm, they aren't just looking at revenue growth. They are scrutinizing cash burn, future competitive moats, and external tech disruption risks. Oura itself flagged AI disruption threats in its regulatory paperwork, reminding investors that hardware business models face constant pressure.
Public market volatility makes pricing a gamble. If a company lists in a choppy market and trades down immediately, employee morale tanks, secondary liquidity dries up, and the stock gets slapped with a "broken IPO" label that can take years to shake off. Smart management teams look at that risk and decide they'd rather stay private.
What This Means for the Rest of the Pipeline
If you are a late-stage founder hoping to ring the bell next year, your timeline just got rewritten. The era of easy public floats based on growth projections alone is dead.
Investors want proof of immediate profitability and pricing discipline. Companies that rely on hype are getting exposed the moment they step onto the public stage. Expect more private rounds, secondary share sales, and structured debt financing as firms kick the IPO can down the road into late 2027 or beyond.
If your business is generating steady cash, don't rush to list just because your venture backers want an exit. Take a page out of the current playbook and protect your valuation until market conditions actually match your worth.