Trillions of passive dollars now chase automated baskets of equities, turning quiet scorekeepers into active market architects. When a handful of companies decide which businesses enter benchmark portfolios and which get left out, they stop measuring market reality and start dictating it.
You might assume an index provider simply looks at a stock exchange, crunches daily trading volumes, and publishes a neutral scorecard. That used to be true decades ago. Today, massive commercial entities like MSCI, S&P Dow Jones Indices, and FTSE Russell do far more than track performance. They design custom benchmarks, dictate capital flows for exchange-traded funds, and quietly steer billions of retirement dollars into specific corporate favorites. When they alter a rule or rebalance a sector, global equity prices shift instantly. They aren't just observing the game anymore. They are writing the rulebook. For a different look, check out: this related article.
The Power of Inclusion
Getting added to a major equity index acts like a golden ticket for any public company. Institutional funds tracking that benchmark must buy your shares immediately, regardless of your near-term earnings outlook or debt load. This creates a massive artificial demand loop. Conversely, if an index committee decides to downgrade or drop a firm, the sell-off can cripple liquidity and make fundraising punishingly expensive.
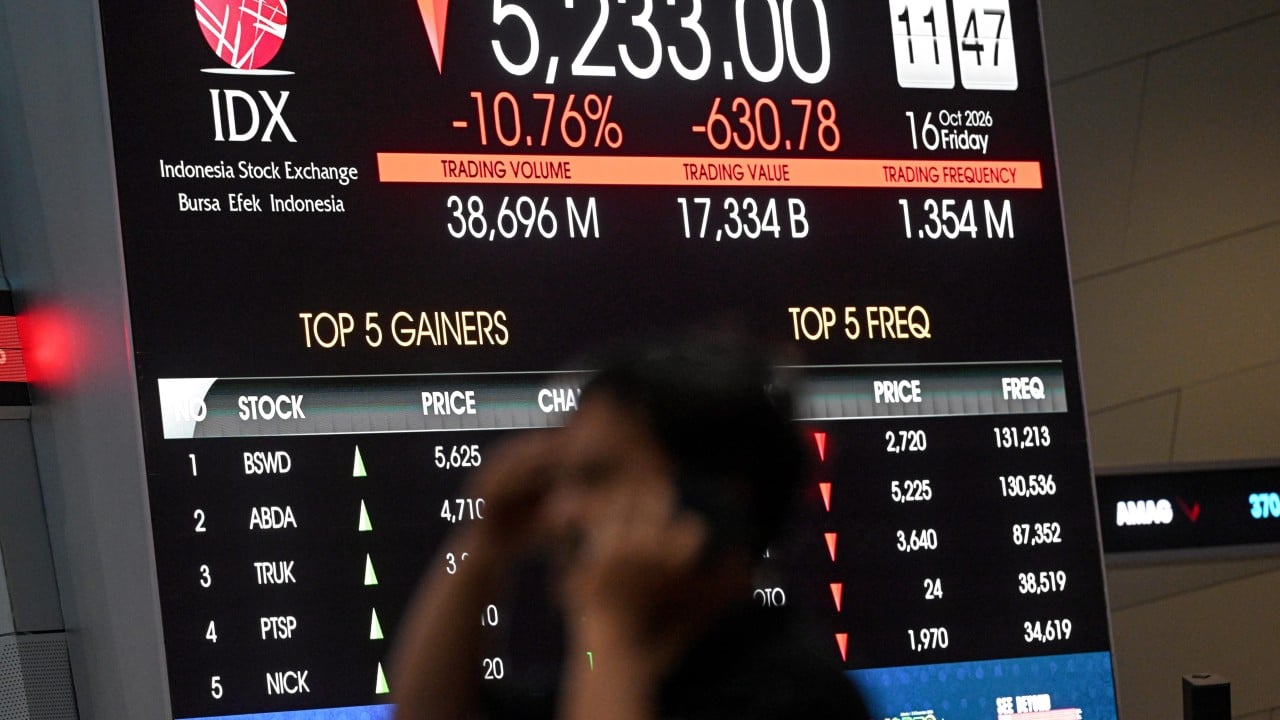
Take recent emerging market adjustments as a practical example. When providers tweak liquidity rules or foreign ownership caps, entire national exchanges scramble to change domestic corporate reporting just to avoid catastrophic index outflows. Companies spend millions restructuring their share registries simply to satisfy an index methodology document written in London or New York. That influence stretches far past traditional securities regulation. Regulators are accountable to voters and legal statutes; index providers answer primarily to commercial revenue targets and licensing fees. Related insight on the subject has been published by Reuters Business.
The Problem with Custom Thematic Benchmarks
The traditional market barometer used to be straightforward: cap-weighted lists measuring the biggest businesses in a country. Now, the industry is churning out bespoke thematic indexes faster than fast fashion brands launch clothing lines.
Investors want exposure to clean energy, artificial intelligence, cyber defense, or localized supply chains. Index companies happily oblige by inventing proprietary scorecards based on vague keyword searches in regulatory filings or qualitative analyst scoring. You end up with portfolios loaded with speculative names that share little more than a marketing buzzword.
When these niche products attract billions in passive capital, valuations detach from economic fundamentals. Small companies trading at absurd multiples get propped up solely because they fit an index provider's thematic narrative. If sentiment shifts, the unwind is brutal because the underlying liquidity dries up just as fast as it appeared.
Who Watches the Watchers?
Financial regulators spent the years following the 2008 crisis cracking down on benchmark manipulation, particularly around interest rate fixes like Libor. Yet equity and bond index providers operate with remarkably light oversight considering their systemic footprint.
Conflicts of interest lurk around every corner. Index firms charge data fees to the very asset managers building products on their benchmarks. They advise companies on how to structure offerings while simultaneously judging whether those same companies meet inclusion criteria. When millions of retail investors rely on these benchmarks for their pensions, a flawed methodology or opaque exclusion decision can cause widespread financial harm without a clear path for legal recourse.
What Investors Must Do Now
You can't boycott index-linked products—they form the backbone of modern retirement investing. But you can stop treating index providers like infallible, neutral referees.
Look under the hood of every exchange-traded fund or mutual fund you own. Read the methodology documents instead of just looking at the catchy fund name. Understand how often the underlying index rebalances and what qualitative screening metrics the provider uses. If a fund's performance relies heavily on a bespoke thematic index with opaque rules, keep your allocation modest. Real diversification means owning assets driven by underlying cash flows and business fundamentals, not just whatever happened to pass an index committee's arbitrary checklist this quarter.